Questions?
We reply within 24 hours, free of charge.
No Thai law requires a private owner to insure a condo unit, house or villa. A bank lending against the property will ask for fire insurance as a condition of the loan. In a condominium, the juristic person usually insures the building and common areas and charges the premium as a common fee — a practice the Revenue Department's 2007 ruling confirms. We couldn't confirm whether the Condominium Act itself makes this a duty, so check the building's bylaws and general-meeting decisions. Your contents, fit-out and liability to others are usually outside that policy, so it's worth checking what you're covered for before you assume you're covered at all.
In short
- Thai law doesn't require a private owner to insure a home; a mortgage lender can, as a loan condition.
- In practice, condo juristic persons arrange building insurance; we couldn't confirm this is a statutory duty, so check the building's bylaws and general-meeting decisions.
- Basic natural-peril cover in a standard policy can carry a low combined annual limit for storm, flood, earthquake and hail together; check the figure and the perils included in your own policy.
- Thailand's new state disaster scheme isn't clearly open to foreign-owned homes; don't rely on it.
- A claim against an insurer must reach court within two years of the loss.
What the condo's juristic person insures and what you insure
In practice, condominium juristic persons arrange insurance for the building and common property, and the premium is billed to owners as a common expense. A 2007 Revenue Department ruling treats that premium as an ordinary shared cost of the building, which is the clearest official confirmation that this practice exists. We couldn't confirm a statutory duty to insure the building in the Condominium Act itself — check the building's bylaws and general-meeting decisions for how your juristic person handles it.
That building policy is written around the structure and common property. Your unit's fit-out, furniture, electronics and your liability if your air-conditioning unit leaks into the flat below are usually a separate matter. We suggest asking the juristic person for the building policy's schedule — the document listing what's insured and for how much — before you assume your contents are covered by it.
| What | Who usually insures it | What to check |
|---|---|---|
| Building and common property | The juristic person, as a common expense | Ask for the policy schedule and the sum insured |
| Your unit's fit-out and contents | You, separately | Whether you have any policy at all |
| Your liability to neighbours or visitors | You, separately | Whether liability is included or needs an add-on |
| A villa's structure | The owner of the house (see below for leasehold) | Who is named as the insured and the beneficiary |
Before buying, see our condo buyer's checklist for Phuket for seven other checks worth running before you pay.
Typical cover: fire, flood, liability
A standard Thai residential fire policy, as insurers and the Office of Insurance Commission describe it, covers fire, lightning, explosion, impact by a vehicle or aircraft, and water damage that isn't from a flood. Storm, flood, earthquake and hail are bundled together under a much smaller limit — insurers commonly quote around THB 20,000 a year in total for all of them combined. If you want real protection against Phuket's rainy-season flooding, you need to ask about an extension; the base policy won't give you much.
Compulsory liability insurance exists in Thailand, but only for certain categories of building under a 2021 ministerial regulation — hotels with 80 rooms or more are the clearest example. A private villa or an individual condo unit isn't on that list, so liability cover for an ordinary home is something you buy voluntarily, not something the law requires.
A new state disaster scheme, and an open question for foreigners
From 1 October 2026 to 1 October 2027, the Department of Disaster Prevention and Mitigation and the Office of Insurance Commission are running a one-year state insurance scheme for homes damaged by flood, windstorm or earthquake: up to THB 100,000 per household for each event, limited to the structure and fixtures, in officially declared disaster areas. A registered house number appears to matter for eligibility, and no extension past October 2027 has been confirmed. We couldn't verify the full official eligibility terms. If your home has no registered house number, ask the Department of Disaster Prevention and Mitigation whether it can still qualify and what evidence is needed. The published terms also don't make clear whether a home owned by a foreigner qualifies at all. Until that's clarified, we wouldn't tell a foreign owner to count on this scheme.
A villa on leased land: who is the beneficiary
Buying a villa on a 30-year leasehold, registered at the Land Department, is the ordinary way foreigners buy a house in Phuket — it isn't a lesser substitute for "real" ownership. Who holds the insurable interest among the leaseholder, the landowner, the building's owner and a mortgage lender isn't something we could confirm from a published source, so the lease and the policy need to be checked against each other, not assumed to line up. What's clear is that you need an insurable interest in the house: under section 863 of the Civil and Commercial Code, an insurance contract does not bind the parties if the insured has no insurable interest in the property.
In practice, that means the lease and the insurance policy need to tell the same story: who owns the house standing on the land, and who is paid if it's damaged. Our lawyers check exactly this point — how the lease records ownership of the house and who the policy names as beneficiary — because a mismatch between the two documents is where disputes start, not where they end. A dispute over what a lease actually guarantees is also why formulations matter long after signing: our typical leasehold "30+30+30" scenario illustrates how a contract may be revised following a court ruling on automatic renewals.
If you're at the stage of deciding how to structure the purchase itself, our guide to buying a villa on a leasehold in Phuket covers registration and renewal in more detail.
If you rent the property out
Thai law doesn't require a landlord to carry liability insurance for an ordinary rental; the 80-room threshold mentioned above is about hotels, not individual owners letting out a condo or villa. What the law does require is a licence if you're renting by the night: letting accommodation for stays under 30 days without a hotel licence is illegal under the Hotel Act, regardless of what insurance you hold. We recommend treating the licence question and the insurance question as two separate problems, because solving one doesn't solve the other.
Our guide to renting out property in Phuket legally sets out what a lawful rental actually requires.
What to check before you sign
Here's what we check in a policy alongside the contract when a client asks us to look at both together:
- Who is named as the policyholder, and who is the beneficiary if there's a claim.
- The sum insured — does it actually reflect what rebuilding or replacing the property would cost.
- The natural-peril limit, and whether you need (and have bought) an extension beyond the basic flood/storm/earthquake bundle.
- What's excluded — every policy has exclusions, and they're worth reading before, not after, a loss.
- Whether the policy matches the lease or the mortgage: the same owner's name, the same property, the same beneficiary where a bank is involved.
- Section 865 of the Civil and Commercial Code: concealing a known material fact when you apply makes the contract voidable, so disclose accurately.
- Section 882: you have two years from the date of the loss to bring a claim to court against the insurer.
If you have a mortgage, the bank will set its own requirement for fire insurance as part of the loan; that's separate from, and usually in addition to, anything described above.
What isn't settled yet
Whether a condo's juristic person has a formal legal duty to insure the building, rather than simply the common and consistent practice of doing so, isn't settled by any section of the Condominium Act we could find — only by the way bylaws and general meetings handle it in practice. Whether a foreign owner's home qualifies for the new state disaster scheme is also unclear from the terms published so far. And the exact wording of exclusions in the official residential fire policy form hasn't been published in a way we could confirm, so treat any list of exclusions you're given as a starting point for questions to your insurer, not a final answer.
What's next
We're not an insurance broker, and we won't recommend one insurer over another. Where we can help is on the legal side: checking that a lease, a purchase contract or a mortgage agreement actually says what you think it says about who owns what and who's paid if something goes wrong.
If you're about to buy, send us your purchase or booking contract: within 48 hours we'll mark the clauses that could become risks, free of charge, including anything about who owns the house and who the insurable party would be. Start with our guide to buying a condo in Phuket with legal support, or, if you're still at the stage of checking the property itself, our property due diligence guide for Phuket.
Phuket areas
The same laws apply across the island, but each area has its own particulars: what kind of property usually sells there, which documents prove rights to the land and what deserves a closer look before you buy.
Kata
In sea-view condominiums the 49% foreign quota usually runs out quickly, so we check it before you reserve a unit.
Patong
People buy condos here to rent out and open businesses that need licences.
Kamala
There are many branded residences here, homes sold under a hotel brand, and the management agreement needs careful reading before you buy.
Old Town
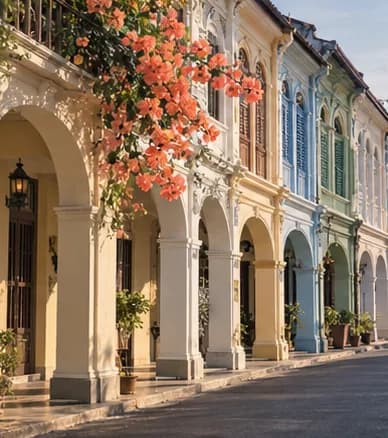
Many historic shophouses, buildings with a shop on the ground floor, are protected and can only be restored under special rules.